Oportun: Savings & Loans
oportunFinanceVerified
- 20.75K Reviews
- 3.9
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
I approached Oportun as a practical finance app rather than a flashy budgeting tool. It is free, aimed at Everyone, and developed by oportun, with a focus on helping people handle savings and loan-related needs from a phone. My overall impression is that it makes the most sense for someone who wants a straightforward place to begin building a savings habit or exploring borrowing options, not for a user looking for a complete investment dashboard or a highly customizable budgeting system.
The app has been available since September 7, 2016, and its current version is 4.177.0. That long presence matters because financial apps need to feel maintained and dependable, although an established product is not automatically the right fit for every financial situation. Oportun has an average rating of 3.9 from around 48 thousand ratings, with roughly 21 thousand written reviews and over a million installs. Those figures suggest a substantial user base, while also reminding me that the experience is not universally smooth.
How Oportun feels to use today
My first reaction is that Oportun is designed for people who prefer a guided financial experience over a blank spreadsheet. The concept is easier to understand than many traditional banking apps: savings and lending are placed close together, so the app can appeal to someone trying to organize short-term money goals while also considering access to credit.
That combination is both its main strength and its main point of caution. Savings and loans are related in everyday life, but they are not interchangeable decisions. Saving gives me more control over timing, while borrowing creates a repayment obligation. I would therefore use the savings side to build a buffer first and treat any loan-related option as a separate decision requiring careful review.
The app is free to download, which lowers the barrier to trying it. However, “free” should not be confused with every financial service being cost-free. When an app connects users with borrowing products, I would always read the complete terms, repayment schedule, interest information, and any applicable charges before accepting anything. The download price tells me about access to the app, not the total cost of a financial product.
A useful starting point for everyday saving
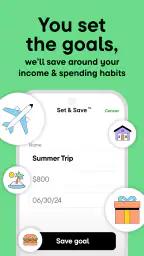
The most convincing use case is a person who repeatedly intends to save but never turns that intention into a routine. For example, imagine I receive income near the end of the week and usually spend whatever remains. Opening the app at that moment could give me a dedicated place to think about a small target, separate from casual spending money. The value is less about a complicated financial theory and more about creating a visible decision: this amount is for a future need, not for today.
I would use it for goals such as an emergency cushion, an annual bill, a modest trip, or replacing an essential household item. These are realistic goals because they benefit from regular contributions and do not require constant market decisions. I would not treat the app as a substitute for professional financial advice, especially if I were dealing with significant debt, irregular income, or a complicated tax situation.
Other Stories to Read




A practical habit is to check the app at the same time as another weekly task, such as reviewing upcoming bills. That makes saving part of a routine instead of something I remember only after spending. I would also keep a small buffer in my regular account so that a savings transfer does not leave me short for necessities. The app can support discipline, but it cannot know every detail of my cash flow unless I actively review it.
Where the lending side needs more attention
Loan access can be useful when an unavoidable expense arrives before I have enough savings. It can also become expensive if I use borrowing to cover ordinary spending month after month. That distinction is important with any finance app, and it is especially important when savings and loans appear in the same overall experience.
If I were considering a loan through Oportun, I would first write down the exact amount needed and the date by which I could realistically repay it. Then I would compare the total repayment with alternatives such as delaying a purchase, negotiating a bill, using existing savings, or checking another lender. A monthly payment that looks manageable can still cost more than expected over the full term.
I would also avoid making a decision while stressed. A broken appliance or urgent bill can make fast access to money feel like the only option. In that situation, I would use the app to review the offer carefully, not simply accept the first available choice. The most useful question is not “Can I make this payment?” but “What will this borrowing change in my budget every month until it is finished?”
What the current version means for users
The current version, 4.177.0, shows that the product is still being developed rather than left untouched. That is encouraging for existing users because finance apps need ongoing maintenance, compatibility work, and attention to the way people manage money on newer phones. Still, a version number by itself does not tell me that every part of the experience has changed or that every past frustration has disappeared.
For someone who already uses the app, the sensible approach is to update through the normal app store process, open the main savings and account areas afterward, and make sure familiar information is still easy to find. I would not assume that a new version changes the terms of an existing financial agreement. Product updates and contract terms are different things, so I would keep copies of important statements and review account notices separately.
New users may benefit from the accumulated refinement of a product that has been around since 2016. Existing users, however, often judge updates by smaller details: whether sign-in is reliable, whether balances are clear, whether support is easy to reach, and whether routine actions take fewer steps. Those are the areas I would watch most closely rather than focusing only on the version number.
The best way to judge the app is by the quality of your regular money routine, not by the number of features on the screen. If it helps me save consistently and understand borrowing decisions, it is doing something valuable. If it encourages me to open a loan screen whenever money feels tight, then I need to step back and reconsider how I am using it.
What existing users should check after an update
I would begin with the basics: confirm that the displayed balance looks right, check recent activity, review any scheduled money movement, and make sure notifications are behaving as expected. I would also verify that contact details and security settings remain current. These checks take little time and are worthwhile whenever a financial app changes version.
Another useful habit is keeping personal records outside the app. A simple note with dates, amounts, and the purpose of each savings contribution can make it easier to spot an error or explain a transaction later. I would not rely on screenshots alone for long-term records, but I would keep important confirmations and statements in a secure place.
People who have used Oportun mainly for loans should review their repayment calendar rather than assuming an update changes payment dates. People who use it mainly for saving should compare the app balance with their own goal plan. This separation helps prevent a common mistake: thinking of the app as one large pool of available money when savings and borrowed money have very different consequences.
How it compares with familiar alternatives
Compared with a traditional bank app, Oportun feels more focused on the connection between saving and borrowing. A bank app may be better if I need broad everyday banking, a wide range of account types, or a single place for established accounts and transactions. Oportun is more appealing when I want a finance-focused experience built around saving behavior and access to loans.
Compared with a dedicated budgeting app, Oportun is not the first tool I would choose for detailed category tracking, long-term reporting, or a full household spending plan. A budgeting specialist usually makes it easier to examine where every dollar goes. Oportun is better suited to the next practical step: deciding what I can set aside and thinking carefully about whether borrowing is appropriate.
Compared with a conventional lender, the app may feel more convenient because the process is designed for a phone. Convenience is not the same as value, though. I would compare the complete cost, payment schedule, and flexibility with other offers before choosing. A familiar brand or simple interface should never replace a proper comparison.
For someone who already has a reliable emergency fund and wants investment research, this probably is not my first recommendation. A savings-and-loans app serves a different purpose from a brokerage platform. Likewise, a person who wants advanced envelope budgeting may be happier with a dedicated budgeting service, while someone seeking only a basic savings account may prefer a conventional bank if that arrangement better matches their needs.
Small workflows that make the app more useful
One non-obvious way I would use Oportun is as a decision checkpoint before borrowing. Instead of opening the loan area only when I am ready to accept an offer, I would first write down the expense, the amount already available, and the monthly payment I can handle without cutting essentials. This turns the app from a quick-access borrowing tool into part of a more deliberate process.
A second useful workflow is separating goals by urgency. I would treat an emergency cushion differently from a planned purchase, even if both are savings goals. If all savings are mentally mixed together, I may spend money intended for an urgent repair on something optional. Clear personal labels or a separate note can preserve that distinction when the app itself does not provide the exact structure I want.
A third tip is to review progress after a real-life change rather than waiting for a monthly reset. A new bill, reduced work hours, or an unusually large expense can make a previous savings plan unrealistic. I would adjust the amount early instead of allowing failed transfers or repeated shortfalls to become a pattern. The app can support a plan, but the plan must keep pace with my actual life.
I would also avoid checking the app compulsively. Frequent balance watching can create the illusion of control without improving decisions. A scheduled review, combined with a simple record of upcoming bills, is usually more useful than opening the app every time I make a purchase.
Remaining gaps and who should skip it
The main limitation is that a focused finance app cannot replace a complete financial system. If I need detailed spending analysis, investment tools, extensive account aggregation, or specialized debt management, I would look elsewhere or combine Oportun with another service. Using several tools can be less convenient, but it may provide a clearer picture than forcing one app to handle every task.
I would also be cautious if my income changes substantially from week to week. A savings routine based on a predictable amount may not fit a freelancer, seasonal worker, or anyone whose essential bills already consume most available cash. In that case, I would prioritize a flexible budget and a cash-flow calendar before committing to regular transfers or a new repayment obligation.
People who are uncomfortable comparing loan terms should not rush into the lending side. The app may make the process feel approachable, but the responsibility remains serious. I would want to understand the total cost and consequences of missed or late payments before proceeding. If those details are unclear to me, that is a reason to pause and seek independent guidance, not a reason to click faster.
Privacy and security habits matter too. I would use a strong, unique password where applicable, protect the phone itself, and avoid reviewing sensitive financial information on an unsecured public device. These are not criticisms unique to Oportun; they are basic precautions whenever a mobile app handles personal money information.
What I would watch going forward
For future versions, I would pay attention to whether routine actions become clearer without making the app feel crowded. The strongest improvements would be practical: transparent explanations, easy-to-follow account activity, dependable notifications, and a clean separation between money I own and money I may borrow.
I would also watch how well the app serves users after the initial sign-up. Many finance products are easy to try but harder to use consistently. Oportun will be more valuable if it continues helping people understand progress, adjust plans when circumstances change, and make informed borrowing decisions instead of simply presenting more financial options.
The store summary highlights recognition as a savings app by Bankrate in 2025 and Forbes Advisor in 2024. I see that as a useful reason to investigate the product, not as a guarantee that it will suit my circumstances. Awards and recommendations cannot determine whether a particular repayment schedule fits my income or whether the savings approach matches my goals.
Overall, I would recommend Oportun to a reader who wants a free, approachable finance app centered on saving and potential loan access, provided that person is willing to read terms carefully and keep borrowing separate from everyday spending. I would skip it as my only financial tool if I needed advanced budgeting, investing, or comprehensive banking features. For the right user, its value is simple: it can make saving feel more intentional while putting borrowing decisions in front of me when I need to think carefully. That is useful, but the app works best when I remain the one making the final financial judgment.
Highlights
- Automated savings tools make it easier to build a financial cushion.
- Loan applications can be completed conveniently from a mobile device.
- Clear repayment schedules help users understand upcoming loan payments.
- Useful account notifications can help track savings and payment activity.
- Designed for everyday users with a relatively straightforward interface.
Limitations
- Loan availability and terms may vary by state and personal eligibility.
- Interest and fees can make borrowing costly if payments are delayed.
- Some features may require identity verification and access to financial data.
- Savings returns may be limited compared with dedicated high-yield accounts.
- Users may receive promotional messages related to loans and financial products.
Frequently Asked Questions
01What is Oportun: Savings & Loans, and who is it designed for?
Oportun is a financial app designed to help eligible users manage money, build savings, and access personal loan products through a mobile device. Its services are generally aimed at people who may have limited or no traditional credit history. Availability, approval, loan amounts, and account features depend on factors such as eligibility, state, identity verification, and Oportun’s current product terms.
02Can I apply for an Oportun loan directly from the app?
In many cases, the app allows eligible users to explore loan options and begin an application from their phone. You may need to provide personal, employment, income, and banking information before receiving an offer. Applying does not guarantee approval, and the final amount, annual percentage rate, fees, repayment schedule, and other conditions vary by applicant. Review all disclosures carefully before accepting.
03How does Oportun’s savings feature work?
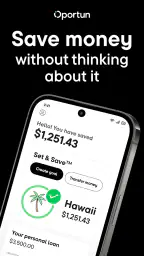
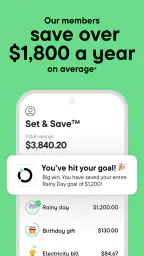
Oportun’s savings tools are intended to help users set money aside automatically or according to a chosen savings goal, depending on the features available in their account. Automatic transfers can make saving more consistent, but users should confirm the amount, frequency, linked bank account, and any applicable restrictions before activating them. Make sure scheduled transfers will not cause overdrafts or insufficient-funds fees.
04Is the Oportun app safe to use, and what information does it require?
Oportun uses account security measures and identity-verification procedures to protect its financial services, but no online platform can eliminate every security risk. The app may request sensitive details such as your name, address, Social Security number, income information, and bank-account data. Download it only from an official app store, use a strong password, enable available security options, and avoid sharing login codes.
05Are there fees or costs associated with Oportun’s loans and savings services?
Costs depend on the specific Oportun product, your location, and the terms offered to you. A loan may include interest and other charges, while savings services may have their own account rules or limitations. Before proceeding, check the agreement for the annual percentage rate, finance charges, late-payment consequences, transfer policies, and any membership or service fees. Never rely only on an estimated payment shown in an advertisement.


